

 We’ve written previously in our blog about the intersection of mobile money and Microfinance and about innovative microfinance products riding on the rails of mobile money. Last week, Nathan Wyeth, Project Director of FrontlineSMS:Credit, visited our office to tell us about the latest developments on the work they have been doing with rural MFIs in Kenya.
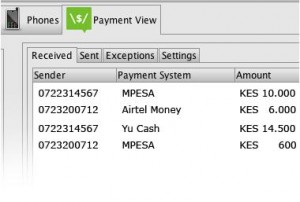
Launched in 2010, FrontlineSMS:Credit is a social enterprise that produces software tools to enable organizations and businesses to easily use mobile money. Realizing that there was a gap in the market for an efficient way of managing organizational data, FrontlineSMS seized this opportunity and linked FrontlineSMS’ existing platform to mobile money.
FrontlineSMS:Credit derives its name from its original target market: MFIs. In the early days of mobile money, MFIs wanted to connect to mobile money services in order improve their processes and reduce their transaction costs, especially in rural areas. However, since MFIs are complex entities in terms of financial needs, FrontlineSMS:Credit has decided to broaden its scope and target a wider group of organizations that also trade directly with the BOP and which could also benefit from mobile money such as NGOs and SMEs. Nathan envisions the role of FrontlineSMS:Credit as that of an interface; a partner for MNOs which helps SMEs, NGOs and MFIs leverage the potential of mobile money.
FrontlineSMS:Credit appears well-positioned to overcome some of the main obstacles that have impeded SMEs and MFIs from adopting mobile money. According to ACCION International, one of the biggest challenges for MFIs is the weakness of their technology infrastructure[1]. For example, ACCION International highlights the difficulty MFIs have in connecting to an MNO’s mobile money platform. FrontlineSMS:Credit works as an interface with operators by providing this service. In addition, a weak country infrastructure (including difficulties to access the internet) often prevents MFIs from using alternative channels. FrontlineSMS:Credit does not require internet access and not only does it provide free turn-key software to organizations, but also serves as an interface, in addition to providing consultancy services to help organizations implement its software when there is no in-house capacity.
FrontlineSMS:Credit is currently running a series of pilots in Kenya with a wide-range of organizations such as a member-owned community-level rural MFI, a microinsurance provider that plans to expand a life insurance and savings product from group to individual distribution through mobile payments, and a final pilot involving local NGOs in Western and Central Kenya which distribute ToughStuff solar products through networks of micro-franchisers.
The software, primarily designed for the Kenyan market, will be publicly released at the end of the year. There are plans to expand to other countries where mobile money services already exist at a large scale, and where there are operators willing to link up their platforms to SMEs and MFIs. We look forward to hearing more about the developments of FrontlineSMS:Credit in the coming months.
[1] In December 2009, ACCION International published a report on the 10 obstacles for MFIs launching alternative channels, including mobile money channels. In particular, the following elements are listed among challenges: “Technological infrastructure remains weak”, “Dedicated and specialized human expertise for channel projects are lacking”, and “MFIs are unsure about how to engage third parties”.
ACCION International, “Accelerating Financial inclusion through Innovative channels. 10 Obstacles for MFIs Launching Alternative Channels – and What Can Be Done About Them”, 2009